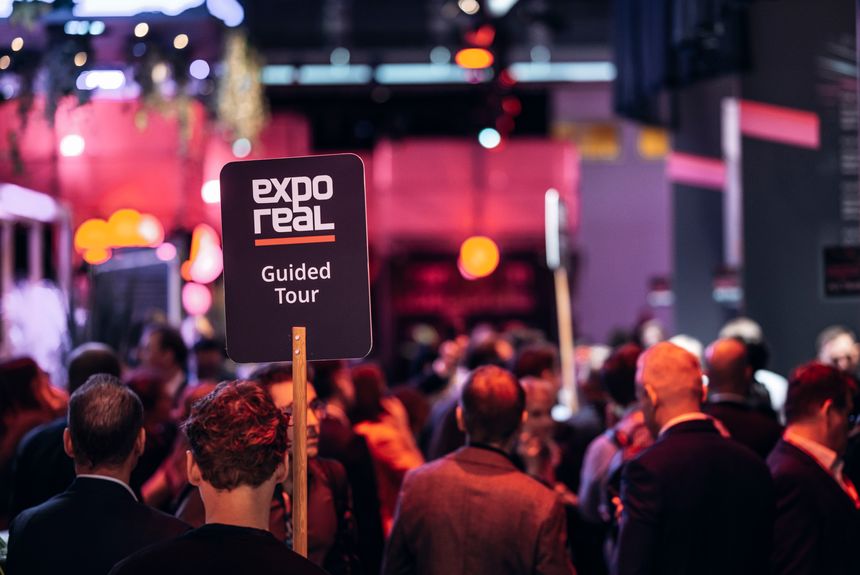
EXPO REAL is one of Europe’s leading real estate events, bringing together investors, lenders, developers and advisers from across the international real estate market.
Deepa Deb and Andy King from Edwin Coe attended this year’s event in Munich, meeting clients and market participants and discussing what the latest trends mean for the UK real estate market.
What has changed since MIPIM?
Six months on from MIPIM, sentiment has shifted. In Cannes earlier this year, there was cautious optimism that easing geopolitical uncertainty and falling interest rates might help drive a broader recovery in real estate investment. By EXPO REAL, the mood felt more pragmatic. The question is increasingly less about when borrowing costs will return to previous levels and more about where value can be created if rates remain higher for longer.
For the UK, transactions are continuing despite the more difficult interest-rate environment. Capital remains available, but investors and lenders are increasingly selective about where it is deployed.
From sector selection to asset selection
One of the clearest themes was the growing focus on the fundamentals of individual assets.
Living, logistics, hospitality and other operational sectors continue to attract interest, but being in a favoured sector is no longer enough. Put simply, owning the right type of real estate does not necessarily mean owning the right real estate.
Location, asset quality, income potential, sustainability and the credibility of the underlying business plan increasingly matter. The importance of location and quality is also becoming more pronounced. In parts of the UK market, strong occupational demand and limited supply are supporting rents for high-quality assets, reinforcing the distinction between the best assets and the wider market.
For investors, this means returns are increasingly likely to depend on growing income, improving the asset and delivering the business plan, rather than simply relying on real estate values rising across the market.
Sustainability also increasingly forms part of that investment case rather than being considered purely through an ESG lens. Energy efficiency and resilience can be relevant to operating costs and the protection of longer-term asset value.
UK value-add is attracting patient private capital
Another particularly interesting theme from conversations in Munich was the amount of family office and private capital looking at UK value-add opportunities, including assets where value might be created through refurbishment, repositioning or more active management.
That matters because family offices and other privately backed investors can often take a genuinely longer-term view. In a market where income growth and improvements to the underlying asset may have to do more of the work, that patience and flexibility could be an advantage.
This sits against a wider backdrop of significant private capital already being deployed into UK real estate. There is also a view in the market that private capital may move ahead of more cautious institutional investors as opportunities emerge.
Repricing in UK real estate may be creating potential entry points for investors prepared to look beyond shorter-term volatility. Rather than waiting for a general recovery in values, patient capital can focus on individual assets where there is a credible route to creating value over a longer investment horizon.
Real estate and infrastructure are converging
The search for value is also taking investors beyond traditional definitions of real estate.
The boundary between real estate and infrastructure is increasingly blurred. Data centres are perhaps the most obvious example, but the trend extends more widely across energy, power and digital infrastructure.
For UK investors, this wider convergence is relevant to how opportunities are assessed, particularly where power availability, energy and digital connectivity can influence the viability and long-term value of an asset.
Financing remains available, but more selective
The financing market reflects many of the same trends.
Debt remains available for the right transactions, but lenders are paying close attention to the individual asset, sponsor, business plan and capital structure.
Higher borrowing costs do not necessarily mean less flexible financing. Where the underlying investment proposition is strong, lenders and borrowers appear increasingly willing to explore structures tailored to the particular asset and business plan.
For investors, the broader message is that leverage alone can no longer be relied upon to make the investment case work. The underlying real estate and business plan increasingly need to stand on their own merits.
Looking ahead
The overriding message from Munich was not that the UK real estate market is suddenly experiencing a broad recovery. Rather, the market is adapting.
The opportunities appear increasingly asset-specific. Investors able to identify strong individual assets, grow income, improve the underlying real estate and take a longer-term view may be better placed to find value.
That environment could be particularly relevant for family offices and other private investors looking at UK value-add opportunities, where patient capital and flexibility can be significant advantages.
Six months on from MIPIM, the conversation has moved on. The focus is becoming less about when the old market conditions will return and more about where value can be created in the conditions we have today.
For more information, please contact a member of our Real Estate Finance team.